A friend at a broker’s office says a hydropower stock is “about to fly.” You have NPR 10 lakh in your Meroshare account. You put NPR 6 lakh into that one name, because if it works, you want it to matter. Three weeks later the company announces a delay at its project site, the stock hits the lower circuit two days in a row, and nobody is bidding. You have lost close to NPR 1.7 lakh before you even had a chance to sell.
The tip was not the real mistake. Tips fail all the time. The mistake was the size. Position sizing on NEPSE is the decision of how much money goes into one stock, and it matters more than which stock you pick, because it decides whether a bad call is a lesson or a disaster. Most retail investors in Nepal spend hours choosing stocks and about four seconds deciding how much to buy. This piece argues that ratio should be reversed, and gives you a concrete set of rules to do it.
Why position size matters more than stock picking
Every investor will be wrong regularly. The question is never “will I be wrong?” but “what happens to my portfolio when I am?”
Position size is what answers that question. If a stock that is 5 percent of your portfolio falls by half, you lose 2.5 percent of your money. Irritating, recoverable, forgettable by next quarter. If a stock that is 40 percent of your portfolio falls by half, you lose 20 percent of everything you own in the market. That is no longer a bad trade. It is a setback measured in years.
The math of recovery makes this worse than it looks. Losses and gains are not symmetric:
- Lose 20 percent, and you need a 25 percent gain to get back to where you started.
- Lose 33 percent, and you need 50 percent.
- Lose 50 percent, and you need 100 percent.
This is plain arithmetic. Small positions keep your losses in the zone where recovery is realistic.
What NEPSE’s rules do to concentrated bets
Position sizing is a universal idea, but NEPSE has features that make concentration more dangerous here than on a large, deep exchange.
The 15 percent daily band cuts both ways
Since April 20, 2026, NEPSE has allowed individual stocks to move up to 15 percent in a single session, up from 10 percent, under the Securities Trading Operation (Fourth Amendment) Regulations, as reported by ShareSansar. The same change widened the pre-open band from 2 percent to 5 percent and moved the market-wide halt to a 15-minute pause at a 5 percent index move and a full-day closure at 8 percent.
Wider bands also mean a concentrated position can lose more, faster. Three consecutive lower-circuit days under the old 10 percent band took a stock down about 27 percent. Under the 15 percent band, three such days take it down about 39 percent (0.85 × 0.85 × 0.85 leaves you with roughly 61 percent of the starting price). If that stock was 40 percent of your portfolio, three bad sessions cost you more than 15 percent of your total wealth in the market.
A circuit is not an exit
When a stock is locked at its lower limit, sell orders pile up and buyers vanish. You can place a sell order. That does not mean it will match. On thinly traded NEPSE names, especially smaller hydropower, microfinance and insurance companies, a stock can sit at the lower circuit with a long queue of sellers and almost no buyers. Your loss on screen is real, and you cannot do anything about it until the selling exhausts itself.
This is why sizing on NEPSE has to account for liquidity, not only price risk. A position you cannot exit is larger than it looks.
The market itself has a long memory of drawdowns
The broad index has shown how deep a fall can go. The NEPSE index closed at a record 3,198.60 on August 18, 2021, according to NEPSE data as compiled by ShareSansar. By November 23, 2023, ShareSansar reported a 52-week low of 1,816.68, a decline of about 43 percent from the peak. That was the diversified index. Many individual stocks fell much further. Your sizing has to survive years like that, not just average weeks.
The real reason Nepali investors over-concentrate
It is worth being honest about why people bet too big. In our view, three habits drive most of it.
The first is the tip economy. A stock arrives with a story attached, a “setting” or a “group” behind it, and the story feels like certainty. Certainty invites size. We have written about why most retail investors lose money on NEPSE, and borrowed conviction is near the top of that list.
The second is the small-portfolio trap. Someone with NPR 2 lakh feels that a 5 percent position (NPR 10,000) “won’t make a difference,” so they go all in on one or two names to make the gains feel meaningful. The logic is backwards. A small portfolio is precisely the one that cannot afford a 50 percent hit, because it is often money the owner will need.
The third is averaging down without a ceiling. A stock falls, the investor buys more to lower the average cost, and a 10 percent position quietly becomes a 30 percent position without any new research. The position grew because the investor was wrong, not because the case got stronger.
A practical position sizing framework for NEPSE
Here is the framework we would use. These numbers are Biznessvue’s opinion, not regulation and not a universal law. They are deliberately simple, because a rule you can follow under pressure beats a clever rule you abandon on a red day.
Rule 1: Cap any single stock at 10 percent at cost
When you buy, no single stock should take more than 10 percent of your total equity portfolio. For a NPR 10 lakh portfolio, that is NPR 1 lakh. If you are new, or the company is small and illiquid, cap it lower, at 5 percent.
Ten percent is not magic. It is a level at which a disaster (the stock losing half its value) costs you 5 percent of your portfolio. You will survive that, and still think clearly about your next decision.
Rule 2: Trim when a winner drifts past 20 percent
Positions grow. A bank you bought at 8 percent of your portfolio might climb to 22 percent after a strong run. That is a good problem, but it is still a problem: your portfolio’s fate is now tied to one company’s next quarterly report.
When any single stock crosses 20 percent of your portfolio at market value, trim it back toward your target. You are not calling the top. You are taking the decision about risk away from your mood. If you hold more than 365 days, the tax cost of trimming is also lower than it was. In September 2026 the government cut capital gains tax on listed shares for individuals, with the short-term rate (365 days or less) reduced to 5 percent, according to the Cabinet decision reported by ShareSansar and nepsetrading.com, and a lower rate for longer holdings. Check the current rate with the Inland Revenue Department before you sell, but tax is rarely a good reason to stay overconcentrated.
Rule 3: Size by the loss you will accept, not the gain you hope for
This is the rule most retail investors have never heard, and it is the most useful one.
Before you buy, decide two things. First, how much of your total portfolio you are willing to lose if this idea is wrong. A common discipline is 1 to 2 percent. Second, the price at which you would admit the idea is wrong. That might be a level where the chart breaks down, or a fundamental trigger such as a missed project deadline.
Then the position size follows from a single division:
Position size = (portfolio × risk percent) ÷ distance to your exit price
A worked example. Your portfolio is NPR 10 lakh. You will risk 1.5 percent on this idea, which is NPR 15,000. You plan to buy a stock at NPR 500 and you will sell if it closes below NPR 400, a 20 percent drop.
NPR 15,000 ÷ 20 percent = NPR 75,000.
So you buy NPR 75,000 worth, which is 150 shares at NPR 500. That is 7.5 percent of your portfolio. If the idea fails and you exit at NPR 400, you lose NPR 15,000, exactly what you planned.
Now try the same stock with a tighter exit at NPR 450 (a 10 percent drop). NPR 15,000 ÷ 10 percent = NPR 1.5 lakh, or 15 percent of the portfolio. Rule 1 caps you at 10 percent, so you buy NPR 1 lakh and your real risk is NPR 10,000. The rules work together: the risk calculation tells you the maximum, the cap stops you from overreaching.
There is a NEPSE-specific catch. Your exit price is a plan, not a guarantee. With a 15 percent daily band and thin order books, a stock can gap straight through your exit level. So for illiquid names, assume your real loss could be 1.5 times your planned loss, and size down accordingly.
Rule 4: Respect liquidity
A useful check: compare your planned position to the stock’s typical daily turnover, which you can see on NEPSE’s website or any market data site. If your position is a large share of what trades on an average day, you will struggle to get out at a fair price when you need to.
As a rough guide (our opinion, not a rule from any regulator), keep any position below about 10 percent of the stock’s average daily turnover. A hypothetical example: if a small hydropower stock trades around NPR 20 lakh a day, a NPR 5 lakh holding is a quarter of a normal day’s volume. On a bad day, when volume dries up and everyone is selling, that could take several sessions to unwind. Large commercial banks rarely pose this problem for retail-sized portfolios. Small promoter-heavy companies often do.
Rule 5: Cap the sector, not just the stock
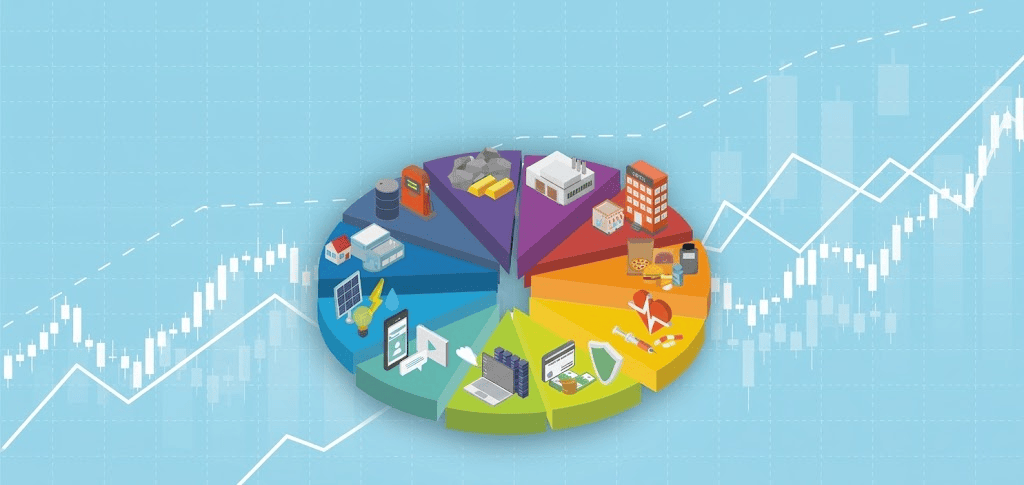
NEPSE is heavily weighted toward banks, hydropower, microfinance and insurance. Owning five commercial banks is not five independent bets. They share the same regulator, the same NRB monetary policy, the same interest-rate cycle and the same bad-loan trends. When NRB tightens, they tend to fall together.
So add a second ceiling: no more than about 25 to 30 percent of your portfolio in any one sector. If you already own three banks and want a fourth, the question is not “is this a good bank?” but “do I want even more of my money riding on one NRB circular?” Our guide to building your first NEPSE portfolio without overconcentrating walks through sector balance in more detail.
Core, satellite and speculation: three buckets, three sizes
Not every position deserves the same size. A simple way to organize this is to sort holdings into three buckets.
Core holdings are established, liquid companies you have researched properly and would hold through a bad year: large commercial banks, Nepal Telecom, profitable insurers with clean books. These can sit at 7 to 10 percent each.
Satellite holdings are reasonable ideas with more uncertainty: a mid-size hydropower company with one operating project, a development bank you like but have not followed long. These belong at 3 to 5 percent each.
Speculative holdings are the tips, the IPO allotments you are curious about, the “setting” stories. If you insist on playing these, cap each at 1 to 2 percent and cap the whole bucket at 10 percent of your portfolio. That way a speculation can be a fun lesson rather than a wound.
The buckets force you to label an idea before you buy it. If you cannot honestly call a stock “core,” it does not get a core-sized position. That one question would have saved our opening investor most of their loss.
How many stocks is the right number?
The opposite mistake exists too. Some investors, having read about diversification, end up with 40 stocks worth NPR 5,000 each. That is not risk management. It is a collection.
Very small positions are expensive to manage on NEPSE. One broker’s published schedule (SSL) charges a flat NPR 10 commission on trades up to NPR 2,500 and 0.36 percent between NPR 2,501 and NPR 50,000, plus a 0.015 percent SEBON fee and a NPR 25 DP charge per stock per transfer day. On a NPR 5,000 sale, that NPR 25 DP charge alone is 0.5 percent of the trade. And you cannot follow 40 companies’ quarterly reports properly.
For most individual investors, somewhere between 10 and 20 stocks, spread across four or five sectors, is enough to avoid single-company disasters while still letting you know what you own. If you cannot be bothered to research even ten companies properly, a mutual fund is the more honest choice.
Margin loans multiply everything
Borrowing to buy shares does not change the rules above. It amplifies them. NRB’s monetary policy for FY 2083/84 (2026/27) raised the single-obligor limit on margin-nature loans against share collateral from NPR 15 crore to NPR 25 crore, as reported by ShareSansar on July 7, 2026. That limit is aimed at large investors, but the logic applies to any amount.
If half your position is borrowed, a 30 percent fall in the stock wipes out 60 percent of your own money in that position, and you are still paying interest. Add a 15 percent daily band and a margin call that arrives while the stock is locked at the lower circuit, and the bank may sell your shares at the worst possible price. Our view is blunt: if you use margin at all, size every leveraged position as if the borrowed amount were already part of your loss.
For NRN investors, one addition: if you cannot watch NEPSE in real time across time zones, favor fewer, more liquid core holdings over a scatter of small speculative names.
The pre-trade checklist
Before every buy order in TMS, answer these five questions. If you cannot, do not place the order yet.
- Is this core, satellite or speculative?
- What percent of my portfolio will this be at cost, and is that within the bucket’s limit?
- At what price will I admit I am wrong, and how much will I lose if I exit there?
- How much of the stock’s average daily turnover does my position represent?
- After this trade, what share of my portfolio is in this sector?
It takes two minutes. Our full checklist for researching a NEPSE stock covers whether to buy. This list covers how much.
The verdict
Position sizing is the least glamorous skill in investing and the one that decides who is still in the market five years from now. NEPSE makes it more important, not less: a 15 percent daily band, thin order books on smaller names, and a market dominated by a handful of closely linked sectors all mean that a single bad stock can do more damage here, faster, than on a deeper exchange.
You do not need a sophisticated model. Cap single stocks at 10 percent at cost. Trim above 20 percent. Size by the loss you will accept. Check liquidity. Cap sectors. And put tips in a small, clearly labeled box. None of this will make your best idea pay more. All of it will make sure your worst idea cannot sink you, and that is the only guarantee any investor can actually give themselves.
This is analysis, not financial advice.
Frequently Asked Questions (FAQs)
1. What is position sizing in NEPSE?
Position sizing means deciding how much money to invest in a single stock to manage risk and protect your overall portfolio.
2. How much should I invest in one stock on NEPSE?
A practical guideline is to limit one stock to 10% of your total equity portfolio. Beginners and investors buying less liquid stocks can consider a 5% limit.
3. How many stocks should I hold in my NEPSE portfolio?
For most individual investors, 10–20 stocks spread across four or five sectors can provide a balance between diversification and manageable research.
4. How do I calculate the right position size?
Divide the amount you are willing to lose by the percentage drop between your buying price and planned exit price. Also, keep your investment within your stock allocation limit.
5. Why is liquidity important when sizing a NEPSE position?
Low liquidity can make it difficult to sell shares when prices fall, especially when a stock hits the lower circuit. Checking average daily turnover helps you avoid investing more than you can reasonably exit.