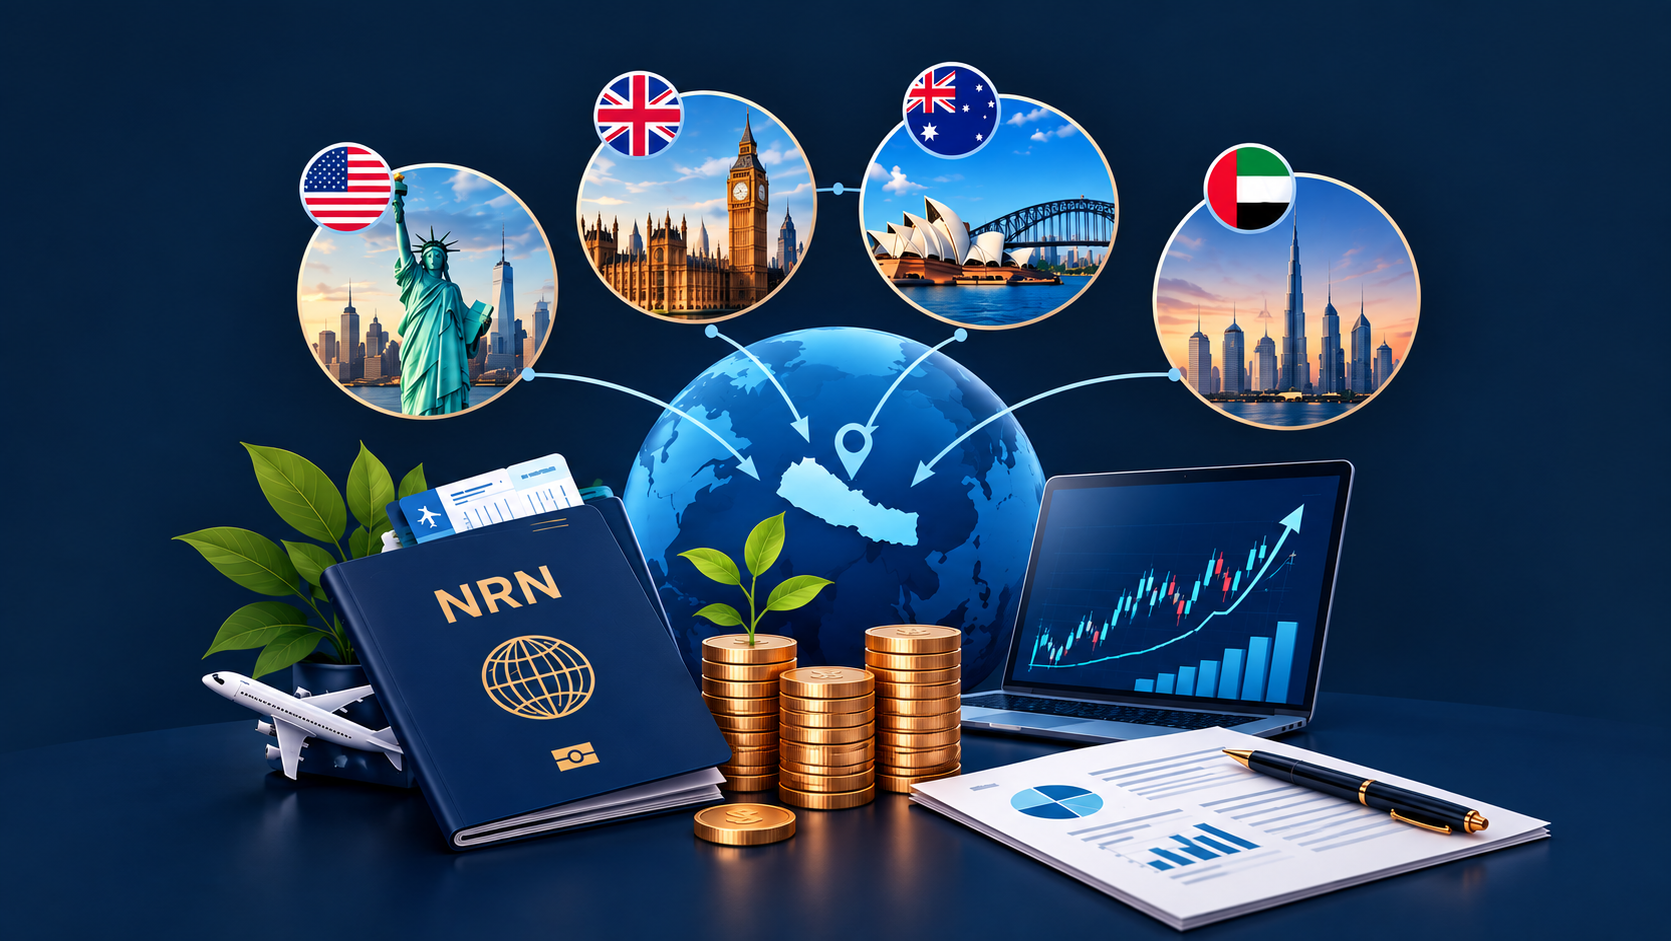
Two Nepali friends buy the same NEPSE stock in the same month. One lives in Dubai, the other in Dallas. They put in the same amount, they sell on the same day two years later, and they wire the money home to the same bank. Their gross gain is identical. Their take-home is not even close. The one in Dubai keeps almost all of it. The one in Dallas hands a chunk to the US Treasury and, if he bought a Nepali mutual fund instead of a single stock, may owe a punitive tax he never saw coming and a filing form most Americans have never heard of.
That gap is the whole point of this piece. When an NRN invests in Nepal from abroad, where you live changes the answer more than which share you pick. The mechanics of buying on NEPSE are the same for everyone. What happens to the money on the way in, and again on the way out, depends on your host country’s banking rules, its tax system, and its currency. Generic NRN advice pretends all of the diaspora is one audience. It is not. A nurse in Melbourne, an engineer in the Gulf, and a student-turned-worker in the UK face three different problems wearing the same NRN card.
The part that is the same everywhere
Before the differences, the common floor. Every NRN, regardless of country, invests through the same Nepal-side plumbing, and it is worth being blunt about what that plumbing does and does not yet allow.
To hold Nepali listed shares as a Non-Resident Nepali you need three things linked together: an NRN identity card, a Non-Resident Nepali foreign-currency (NRFC) account at a Nepali commercial bank, and an NRN demat account with a broker to transact. The foreign-currency account is not optional decoration. It is the piece that keeps your money inside a dollar-in, dollar-out corridor that Nepal Rastra Bank can trace end to end, which is what makes your eventual sale proceeds repatriable. Send money through a relative’s ordinary rupee account instead and you may own a winning position you cannot cleanly get out. We walk through that trap in detail in our guide to NRN foreign-currency accounts and what’s allowed.
Here is the honest caveat that applies to all countries equally. Direct, open secondary-market access for individual NRNs is still being built. As of 2026, SEBON has been finalizing the legal provisions and working procedures that would let NRNs buy and sell listed shares directly, and a feeding study report has floated conditions including a suggested ceiling on how much an individual NRN could transact. Treat that as planned, not live. The broad structure of how NRNs can invest in NEPSE today is real, but anyone telling you the door is fully open should be read with skepticism.
On the Nepal tax side, the bite is small and mechanical, and it is the same for an NRN in any country. A cash dividend from a listed company is taxed at 5 percent, withheld at source, as a final tax under the Income Tax Act. Share capital gains, under the Finance Bill for fiscal year 2082/83 (2026/27), are taxed at 7.5 percent for shares held over one year and 10 percent for shares held one year or less, again as a final tax. Nepal takes its small cut and closes the matter. That is the floor everyone stands on. The differences all come from the second country.
Why the country changes everything
Double taxation, or the lack of it, turns on one fact: whether your host country taxes your worldwide income, and whether it does so at a rate above Nepal’s small final tax.
Countries fall into three rough camps for an NRN investor. There are zero-tax jurisdictions, mostly the Gulf, where there is no second tax at all. There are worldwide-tax countries with credit relief, like Australia and the UK, where you get taxed at home but can offset the Nepal tax already paid. And there is the United States, which also taxes worldwide income but layers on a reporting and anti-avoidance regime harsh enough to deserve its own category. The phrase “NRN invest from abroad Nepal” hides all three behind one label. Sort yourself into the right camp before you model a single return.
One more shared reality cuts across all three: the rupee. Whatever your tax outcome, your gain is earned in Nepali rupees and spent in dollars, pounds, or dirhams. The Nepali rupee is pegged to the Indian rupee, and the Indian rupee has drifted lower against the US dollar for years. A NEPSE position that rises 30 percent in rupees can hand back a meaningful slice of that when converted home. We treat this in full in the currency risk NRNs carry investing in NEPSE. Hold it in mind through every country below, because none of the tax math rescues you from a falling exchange rate.
The Gulf: the easiest case, by a wide margin
Start with the best outcome, because a large share of the diaspora lives inside it. The UAE, Saudi Arabia, Kuwait, and the rest of the Gulf states levy no personal income tax and no capital gains tax on individuals. Per PwC’s Worldwide Tax Summaries and the respective authorities (ZATCA in Saudi Arabia, for example), salaries, rental income, and capital gains for individuals are all untaxed in these jurisdictions as of 2026.
Work through what that means for a NEPSE trade. Your gain is taxed once, in Nepal, at the small final rate. Your host country does not tax it again because it does not tax your investment income at all. There is no second claim, so there is nothing for a treaty to prevent. This is the situation where the missing DTAA that worries so many NRNs is simply irrelevant. Double taxation needs two taxing countries. In the Gulf you have one.
Qatar is the technical exception that proves the point. Qatar is the only Gulf state with a Double Taxation Avoidance Agreement in force with Nepal, according to reporting on Nepal’s treaty network, but since Qatar also does not tax individual investment income, the treaty changes little for a salaried NRN there. Practically, whether you are in Doha, Dubai, or Riyadh, your Nepal return comes home taxed only by Nepal.
So the Gulf NRN’s real enemies are not tax authorities. They are the two things this article keeps returning to: getting the money in and out through the right account, and the exchange rate. Get the NRFC structure right, and your biggest leakage is currency, not tax. That is a genuinely good position to be in, and Gulf-based investors should not talk themselves into complexity they do not have.
Australia: taxed at home, but credited
Australia is the clean example of the middle camp. Australian tax residents are taxed on their worldwide income, including foreign capital gains and dividends, generally at their marginal rate, which for most working professionals sits well above Nepal’s single-digit final tax. On its face that looks like double taxation.
It usually is not, because Australia grants a foreign income tax offset for tax already paid to another country on the same income. You declare the Nepal gain on your Australian return, calculate the Australian tax on it, and subtract the Nepal tax you already paid. You do not pay both in full. You pay the Nepal tax, then top up to the Australian level. The total is the higher of the two countries’ effective rates on that income, not the sum.
A worked example makes it concrete. Say an Australia-resident NRN makes a NPR 5 lakh long-term gain on NEPSE shares. Nepal withholds roughly 7.5 percent, about NPR 37,500, as final tax, and the net comes home. Australia then assesses the full gain at the investor’s marginal rate. Because the Nepal tax is offset, the investor tops up to the Australian figure rather than paying it twice. Nepal has no DTAA with Australia, but here the treaty’s absence barely matters, because Australia’s unilateral offset does the same job a treaty would. What the Australian NRN must not do is assume the Nepal 5 percent dividend withholding is the end of it. It is the end of it in Nepal. In Australia the income is still declarable, and the offset only exists if you file for it and can prove the Nepal tax was paid.
The United Kingdom: worldwide income, and a rule that just changed
The UK belongs in the same middle camp as Australia, but with a twist that recently caught out exactly the kind of person reading this. UK tax residents are taxed on their worldwide income and gains, and as of April 6, 2025, the old remittance basis for non-domiciled residents was abolished. Under the previous system, a non-dom could keep foreign income and gains untaxed in the UK as long as the money was not brought into the country. That door is closed. Per GOV.UK, all UK residents are now taxed on the arising basis, meaning foreign income and gains are taxable as they arise, whether or not you remit them to Britain.
Why does this matter to an NRN? Because a lot of diaspora investors quietly relied on the old rule without knowing its name. If you kept your NEPSE gains in Nepal and never wired them to the UK, you may have assumed they were invisible to HMRC. After April 2025 that assumption is wrong. The gain is taxable in the UK when it arises, sitting in a Kathmandu account or not.
There is one relief worth knowing. The UK replaced the remittance basis with a four-year Foreign Income and Gains (FIG) regime for new arrivals: individuals who become UK resident after at least ten consecutive non-resident years can exempt foreign income and gains for their first four UK tax years. So a recently arrived Nepali professional may have a genuine window where NEPSE gains escape UK tax entirely. A settled, long-term UK resident does not. As with Australia, the UK offers foreign tax credit relief for the Nepal tax paid, so the practical outcome for a settled resident is a top-up to the UK rate, not a double charge. But the reporting obligation is now unavoidable, and the country-specific point is stark: the same NEPSE trade that was fine to leave unreported from London in 2023 is a filing item from London in 2026.
The United States: its own category
The US taxes its citizens and green-card holders on worldwide income no matter where they live, which already puts American NRNs in the worldwide-tax camp. The foreign tax credit exists here too, so the Nepal tax on a dividend or a direct share sale is generally creditable against US tax. If an American NRN buys individual NEPSE shares, the outcome resembles the Australian case: declare it, credit the Nepal tax, top up to the US rate.
The landmine is mutual funds. A Nepali mutual fund, or any pooled foreign fund, is very likely a Passive Foreign Investment Company (PFIC) in US tax law. PFICs are taxed under a deliberately punitive regime designed to remove any advantage from holding investments through foreign funds, and each one generally requires its own Form 8621 filing. The tax treatment of PFIC gains and distributions can be materially worse than the treatment of the same money held in a single stock. The blunt planning implication: an American NRN who wants Nepal exposure should think hard before buying a Nepali mutual fund, and should get US tax advice first. The instrument that looks simplest from Kathmandu can be the most expensive from the US side.
Then there is reporting, which is not optional and not trivial. A US person with foreign financial accounts exceeding USD 10,000 in aggregate at any point in the year must file an FBAR. A single filer living abroad with specified foreign assets above USD 200,000 may also owe Form 8938. Your NRFC account and your demat holdings can trip these thresholds. Skipping the filings does not save tax; it creates an undeclared-foreign-account problem, which is a worse and more expensive category of trouble than the tax itself.
The verdict: sort yourself first, then invest
The single most useful thing an NRN can do before buying a NEPSE share is to correctly place their host country in one of three buckets. If you live in the Gulf, your investment income faces one small final tax in Nepal and nothing else, so spend your energy on the account structure and the exchange rate, not on imagined tax problems. If you live in Australia or the UK, you will be taxed at home on worldwide income, but a credit for the Nepal tax means you top up rather than pay twice, provided you actually declare the income and keep the withholding paperwork. If you live in the US, treat it as its own game: individual shares are manageable, Nepali mutual funds are a PFIC trap, and the reporting forms are mandatory.
Across all three, two things never change. The money has to travel through the right foreign-currency channel or it may never come home, and the rupee will quietly tax every repatriation regardless of what any government does. Where the tax picture gets even slightly complex, and it does for most US and many UK readers, pay an accountant in your country of residence who has handled foreign income before. It is the cheapest insurance on the whole investment. The country you live in wrote half your return before you picked a single stock. Read that half first. For the mechanics of who taxes what and why most of the diaspora has no treaty at all, our companion piece on NRN double taxation and DTAA goes deeper.
This is analysis, not financial advice.
Frequently Asked Questions
1. Can NRNs invest in Nepal from abroad?
Yes. NRNs can invest in Nepali listed shares using the required Nepal-side setup, including an NRN identity card, NRFC foreign-currency account, and NRN demat account with a broker. However, as of 2026, direct open secondary-market access for individual NRNs is still being developed.
2. How is NRN investment income taxed in Nepal?
For NRNs, listed-company dividends are subject to 5% tax. Share capital gains are taxed at 7.5% for shares held for more than one year and 10% for shares held for one year or less, according to the article’s 2026/27 tax treatment.
3. Do NRNs in Australia and the UK have to pay tax on Nepal investments?
Generally, yes. Australia and the UK generally tax residents on worldwide income and gains. However, eligible foreign tax credits can help reduce double taxation for Nepal tax already paid.
4. Do NRNs in the US have to report their Nepali investments?
Yes, US citizens and green-card holders are generally taxed on worldwide income. Depending on their holdings, they may also have foreign-account reporting obligations such as FBAR and Form 8938. Nepali mutual funds can also create PFIC tax and reporting issues, including Form 8621.
5. What should NRNs consider before investing in Nepal?
NRNs should first understand the tax rules of their country of residence, use the correct NRFC/foreign-currency channel, understand currency risk, and keep proper tax and investment records. For more complex situations, especially in the US and UK, consulting an accountant experienced in foreign investment income is recommended.